
Insurance
Strata Insurance Claims: What You Must Tell the Insurer and Who Gets the Payout
The owners corporation holds the building policy, so it is the insured, it carries the duty of disclosure and it usually gets the money. Here is who can lodge a claim, what a building must tell its insurer, where the payout goes, and what to do when a claim stalls or is declined.
By Buddy · · 13 min read
On this pageThe owner briefingOn this page
- The owner briefing
- Quick answers
- How does the strata insurance claim process work?
- Can I lodge a claim on strata insurance as an owner?
- What happens if the building didn't disclose something to the insurer?
- Who gets the strata insurance payout?
- What can I do if a strata insurance claim is declined?
- Who the policy belongs to
- Who can lodge a claim
- What the building must tell the insurer
- What non-disclosure costs a building
- The claim, step by step
- Who gets the payout, and where it must go
- Cash settlement or repair
- When a claim is slow or declined
- The state-by-state table
- Owner checklist
- Committee checklist
- How UnitBuddy fits
- Related reading
- Sources and further reading
The owner briefing
- The owners corporation is the insured on the building policy. It lodges building claims, and the insurer pays it or its repairer. Many policies also let a lot owner lodge for damage inside their own lot.
- The building has to tell the insurer what it knows about the risk: open defects, cladding, past claims, works under way. What the insurer can do if it wasn't told is set by the federal Insurance Contracts Act 1984, not by the strata Acts.
- A declined claim does not end the owners corporation's repair duty. If a claim stalls, complain to the insurer in writing first, then go to the Australian Financial Complaints Authority, which is free.
A ceiling comes down after a storm. Someone has to ring the insurer, someone has to pay the builder, and six owners want to know when their kitchens will be fixed. The strata policy pays for most of it. The arguments start over who lodges, what the building told the insurer at renewal, and where the money goes when it arrives.
This guide works through those three questions, then delays and disputes, then what each state's strata Act adds.
Quick answers
How does the strata insurance claim process work?
Make the building safe, photograph everything, then tell the strata manager or committee and the broker the same day. The owners corporation, or someone acting for it, lodges the claim with the insurer. The insurer may send a loss assessor, then accept, partly accept or decline. If it accepts, it either repairs through its own builders or pays a cash settlement. The building pays the excess. The claim, step by step has the order.
Can I lodge a claim on strata insurance as an owner?
Often, yes, for damage inside your own lot. Many strata policies and insurers accept a claim lodged by a lot owner for their lot, and some prefer it to go through the strata manager or broker. Check the policy wording or ask the broker. Damage to common property is the owners corporation's claim. In the ACT the Act says the owners corporation must lodge building claims (s 100A).
What happens if the building didn't disclose something to the insurer?
The insurer may reduce the claim, and in a fraud case it may cancel the policy. Those remedies come from the Insurance Contracts Act 1984, section 28 for general insurance. A defect the committee knew about and didn't mention is the usual problem. The duty of disclosure explains what to tell.
Who gets the strata insurance payout?
The owners corporation, because it holds the policy, or a repairer the insurer pays directly. For damage inside a lot, some insurers pay the lot owner directly or through the owners corporation. Ask the insurer, in writing, who it will pay before anyone signs a settlement.
What can I do if a strata insurance claim is declined?
Ask for the reasons in writing. Complain to the insurer through its internal complaints process. If that fails, take it to AFCA, which is free for the complainant. While that runs, the owners corporation still has to repair common property. In NSW that duty is section 106 of the Strata Schemes Management Act 2015.
Who the policy belongs to
Every state and territory makes the owners corporation (body corporate in Queensland and Tasmania, strata company in WA) insure the building. In NSW that is a damage policy for full replacement cost under section 160. What is strata insurance covers each state's version and what the policy does and doesn't cover.
That one fact settles most claim questions. The owners corporation is the insured. It signs the proposal, it carries the duty of disclosure, it pays the excess and it is the default payee. You pay for the policy through your levies, but you are not the one who holds it.
Lot owners still have a stake. The Insurance Contracts Act has a section on third-party beneficiaries (section 48): a person the policy names or refers to as someone the cover extends to can claim under it, even though they did not sign it. Many strata policies name lot owners as insureds for their lot. That is why an owner can often lodge directly. Your policy wording decides how it works for your building.
Who can lodge a claim
There are three common setups:
- Common property damage. A roof, a façade, a lift, a shared pipe. The owners corporation lodges. In practice that is the strata manager, the broker or a committee member the committee has authorised.
- Damage inside your lot covered by the building policy. Original ceilings, walls, built-in cupboards and fixtures. Many policies let you lodge yourself. Others want it through the manager or broker so one claim covers every lot hit by the same event.
- Your own belongings and upgrades. Furniture, a new kitchen you installed, floating floors. That is your contents or landlord policy, not the strata policy. Our contents versus strata guide draws the line.
If the owners corporation won't lodge a claim for damage that the building policy covers, put the request in writing with photos and the date. If it still won't act, and your policy lets owners lodge, lodge it yourself and tell the committee you did. If the policy doesn't let you, your state's strata tribunal can deal with an owners corporation that won't perform its duties. The water leak guide sets out the tribunal in each state.
Tell the insurer early, whoever lodges. The Insurance Contracts Act stops an insurer refusing a claim just because of something the insured did after the policy started, such as reporting late, but it lets the insurer reduce the claim by the amount that delay cost it (section 54). A leak that ran for three months while emails went back and forth can cost the building real money.
What the building must tell the insurer
Before the policy starts and before each renewal, the insured has a duty of disclosure under section 21 of the Insurance Contracts Act. In broad terms, it must tell the insurer every matter it knows is relevant to the insurer's decision to insure and on what terms, or that a reasonable person in the circumstances could be expected to know is relevant. The insurer has to tell the insured about that duty in writing (section 22). Both sides also owe each other the utmost good faith (section 13).
There is a second regime. For contracts entered into or renewed since 5 October 2021, "consumer insurance contracts" under section 11AB use a duty to take reasonable care not to make a misrepresentation (section 20B) instead. Which regime applies to a strata building policy turns on that definition, so ask your broker which one the insurer says applies to yours. The practical advice is the same under both: answer every question fully, and volunteer what a reasonable insurer would want to know.
For a strata building, that usually means:
- Known defects. Water ingress, waterproofing failures, cracking, concrete cancer, fire safety orders, and any defect report or building bond claim.
- Cladding. Whether the building has combustible cladding, whether it has been tested or removed, and any council or regulator order.
- Claims history. Past claims, including declined ones and claims with other insurers.
- Works and vacancy. Major works under way, lots or floors left vacant, and changes in use, such as a commercial tenancy or short-stay letting.
- Anything the questions ask. If the proposal or renewal form asks, answer it fully and in writing.
Assume that what your committee and strata manager know, the insurer will treat as known to the owners corporation. The broker can only pass on what it is given.
What non-disclosure costs a building
For general insurance, section 28 sets the insurer's remedies. If the failure was fraudulent, the insurer may avoid the contract. Otherwise it can reduce what it pays to the amount that puts it where it would have been if it had been told. If the insurer would have excluded water damage from a known leaking podium, a water claim from that podium may be cut to nothing. If it would have charged a higher premium, the claim may be reduced in proportion.
That cut lands on every owner. The repair still has to be done, and the shortfall comes back as a special levy.
My view: tell the insurer about the defect. A higher premium or a specific exclusion you can see is cheaper than a reduced claim you discover after the ceiling falls in.
The claim, step by step
- Make safe. Turn off the water, isolate power, move people if needed. Emergency make-safe work is normally part of the claim. Photograph before anything is removed.
- Tell the right people the same day. The strata manager or committee, the broker, and any affected neighbour. Put it in writing.
- Find the cause. A plumber, roofer or leak detector writes a short report on what failed and whether it is common property or lot property. Insurers decide on cause.
- Lodge. Use the insurer's claim form or the broker. Attach photos, the cause report, quotes and the policy number.
- Assessment. The insurer may send a loss assessor or ask for more information. Answer quickly and keep copies.
- Decision. The insurer accepts, partly accepts or declines. Ask for any decline or part-decline in writing with the policy clause it relies on.
- Repair or cash. The insurer repairs through its builders or offers a cash settlement. See below before you agree to either.
- Excess and close-out. The owners corporation pays the excess. Who ends up carrying it depends on your state and by-laws. Who pays the strata insurance excess has each state's rule.
The insurance industry's General Insurance Code of Practice, published by the Insurance Council of Australia, sets service standards for insurers that subscribe to it. The version in force took effect on 5 October 2021 and was last updated in October 2023. Its claims part says the insurer will update you at least every 20 business days, tell you its decision within 10 business days of having all the information, and decide within 4 months of receiving the claim, with exceptions such as a major catastrophe (paragraphs 70 and 76 to 78). That part applies to "retail insurance". It doesn't apply to "wholesale insurance", and a policy held by an owners corporation may fall on either side of that line. Ask the insurer, in writing, whether it treats your policy as retail under the Code. If it does and it misses a timeframe, quote the paragraph in your complaint.
Who gets the payout, and where it must go
The default payee is the owners corporation, because it is the insured. Often the money never passes through the building's account: the insurer pays its own builder, or pays the owners corporation's contractor against an invoice.
Where the money does arrive, it is the owners corporation's money held for the repair. Spend it on the repair it was paid for. Two states write this down:
- Victoria. If the owners corporation has a maintenance fund, insurance money for damage to property covered by the approved maintenance plan must be paid into that fund (s 42 of the Owners Corporations Act 2006).
- Queensland. Under the Standard Module, insurance money for damage to property must be applied to the repair or replacement as soon as practicable, unless a resolution without dissent decides otherwise (s 208).
I could not confirm a similar written rule in the other states' Acts. Check the insurance part of your Act before the money is moved.
Two situations need care:
- Damage inside a lot. If the insurer pays the owners corporation for lot damage, such as a ceiling or built-in wardrobe, that money is for that lot's repair. The committee should either arrange the repair or pass the money to the owner, and record which it did in the minutes.
- Common property failure, claim declined. The owners corporation still has to repair common property. In NSW the duty under section 106 is strict, and an owner who suffers loss from a breach can claim damages under section 106(5). Victoria's repair duty is section 46. A decline is an insurance outcome. It is not a finding that nobody has to fix it.
Cash settlement or repair
A cash settlement moves the risk from the insurer to the building. If the builder's final bill comes in over the settlement, the owners corporation pays the difference, and the repair duty doesn't shrink to fit the cheque.
Before the committee accepts cash:
- Get the insurer's scope of works and its figure, line by line.
- Get an independent quote for the same scope. Check it includes professional fees, make-safe, debris removal, compliance upgrades the work will trigger, and GST if the building isn't registered for it.
- Ask whether the settlement includes lot damage, and how that part will reach the affected owners.
- Don't sign a release until the scope is agreed. A release usually ends the claim for that event.
If the insurer repairs through its own builders, ask who warrants the work and for how long, and put that in the building's records. Defects in an insurer's repair are a common second dispute.
When a claim is slow or declined
Go in this order.
- Ask in writing. Ask for the reason, the policy clause relied on and a copy of any assessor's report.
- Complain internally. Use the insurer's complaints process, and say plainly that it is a complaint. ASIC's Regulatory Guide 271 sets the maximum time for a firm to answer a standard complaint. Insurers that subscribe to the Code also promise a decision on a complaint within 30 calendar days, and that part of the Code applies to every policy it covers (paragraph 147).
- Take it to AFCA. If the insurer's answer doesn't resolve it, or the deadline passes, lodge with the Australian Financial Complaints Authority. It is free for the complainant, and AFCA's decisions bind the insurer if you accept them. Check AFCA's eligibility and limits for your claim on its site.
- Fix the building anyway. Don't wait for AFCA to repair an active leak. Keep invoices, because a later win can repay them.
For a sense of how an insurer handles complaints, AFCA's Datacube publishes complaint numbers and resolution times by firm. Strata insurers compared explains how to read it, since the figures sit with the insurer behind the strata agency.
A dispute between an owner and the owners corporation, such as a committee that won't lodge or won't pass on lot money, is not AFCA's business. That goes to your state's strata dispute process and tribunal.
The state-by-state table
The Insurance Contracts Act, the Code and AFCA apply everywhere. The strata Acts add rules on who must insure, who pays the excess and, in a few places, how claims and money are handled. Where I could not confirm a claim-specific rule, the table says so.
| State | Legislation | Claim or payout rule I could confirm | Check yourself |
|---|---|---|---|
| NSW | SSMA 2015 | Damage policy for full replacement cost (s 160). Repair duty continues if a claim is declined (s 106) | Who lodges and how money is applied: not confirmed. Read the Act's insurance part |
| Vic | OC Act 2006 | Insurance money for items in a maintenance plan goes to the maintenance fund, where there is one (s 42). Excess levy in set cases (s 23A) | Who lodges: not confirmed |
| Qld | BCCM Act 1997; Standard Module | Excess split by one-lot and multi-lot events (s 203). Insurance money applied to the repair as soon as practicable unless a resolution without dissent decides otherwise (s 208) | Other modules: check your module's insurance part |
| WA | Strata Titles Act 1985 | None confirmed | Read the Act's insurance provisions |
| SA | Strata Titles Act 1988; Community Titles Act 1996 | Community schemes: excess or under-insurance shortfall met by the corporation (s 103(3)) | Strata schemes: not confirmed |
| Tas | Strata Titles Act 1998 | Body corporate pays the excess except on a one-lot event; no subrogation against an owner unless the act was wilful (s 99) | Payout rules: not confirmed |
| ACT | UT(M)A 2011 | Owners corporation must lodge building claims and pay the excess (s 100A). Recovery for wilful or negligent acts (s 31) | Payout rules: not confirmed |
| NT | Unit Title Schemes Act 2009; Unit Titles Act 1975 | None confirmed | Read the Act and your scheme's by-laws |
Owner checklist
Committee checklist
How UnitBuddy fits
UnitBuddy gives the building one shared record. The committee can keep the certificate of currency, policy wording and each claim file in documents, record decisions about lodging, settlement and excess with reasons, and send notices to affected owners. Asset records show which items keep failing, and the finances view tracks premiums and excesses against the budget. UnitBuddy doesn't hold or move money and isn't trust accounting software, so claim payments still go through the scheme's own account.
Related reading
- What is strata insurance? What it covers and what it doesn't
- Who pays the strata insurance excess? The rules by state
- Strata insurers compared: CHU, SCI, Flex, QUS and Longitude
- Water leaks from above: who pays and how to force a repair
Sources and further reading
- Insurance Contracts Act 1984 (Cth), ss 11AB, 13, 20B, 21, 22, 28, 48 and 54
- General Insurance Code of Practice (updated October 2023), via the Insurance Council of Australia
- ASIC Regulatory Guide 271: internal dispute resolution
- Australian Financial Complaints Authority and the AFCA Datacube
- Strata Schemes Management Act 2015 (NSW)
- Owners Corporations Act 2006 (Vic)
- Body Corporate and Community Management (Standard Module) Regulation 2020 (Qld)
- Strata Titles Act 1998 (Tas)
- Unit Titles (Management) Act 2011 (ACT)
What changed in strata this month? Read the strata news for your state, with every figure sourced.
More guides like this
Guides
Strata Finance & Levies in Australia: The Complete Committee Guide (2026)
Everything Australian strata committees and owners need to understand about levies, capital works funds, insurance, hidden fees, and the financial decisions that shape building life. State-by-state, plain English.
5 May 2026 · 14 min read
Insurance
Storms, Floods and Cyclones: How a Strata Building Prepares, and What Insurance Covers
Before storm season a strata building needs clear drains, working pumps and secured balconies. Here is the committee's pre-season checklist, how storm, flood and actions of the sea differ in a strata policy, what the northern cyclone pool does and doesn't do, and what to do in the week after.
19 November 2026 · 13 min read
Insurance
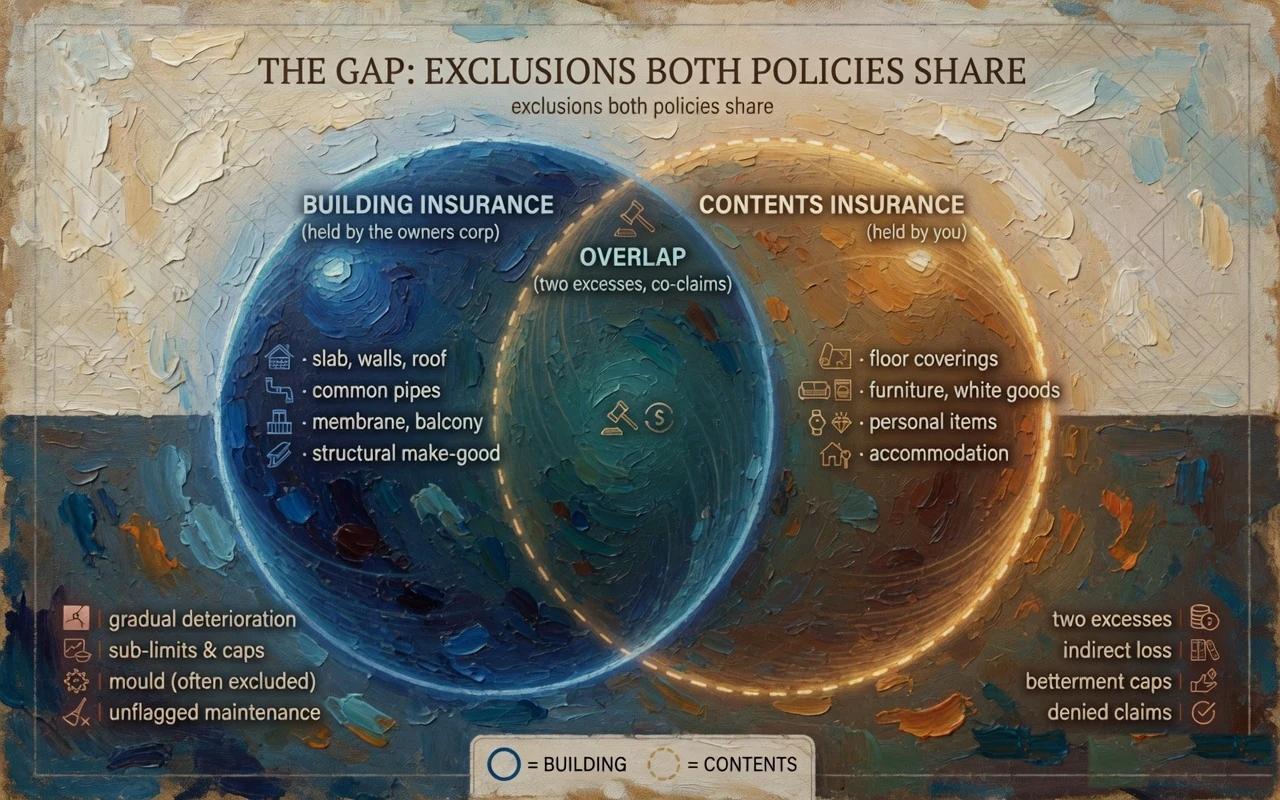
Who Pays the Strata Insurance Excess? The Rules by State
The owners corporation holds the building policy, so it pays the excess first. Queensland, Victoria and Tasmania have written rules that can move it to one owner. NSW and WA leave it to by-laws. Here is each state's rule, when you can be charged, and the one-page policy that stops the argument.
19 November 2026 · 13 min read